Distribution trends: the rise of active ETFs and the integration of AI into fund selection

14 SEPT, 2026


Active ETFs have moved from a niche wrapper to one of the fastest-growing segments of European fund distribution, while artificial intelligence is reshaping how selectors screen and monitor the managers behind them. Together, the two trends are redefining what due diligence looks like for private bankers, fund selectors and asset managers.
A structural shift in the ETF wrapper
Europe's active ETF market has moved from the margins of the industry to a genuine growth segment. According to EFAMA, the UCITS active ETF market expanded by 385% over five years, reaching €49 billion in assets under management by the end of 2024 after €16.3 billion of net inflows that year. Morningstar data shows the pace has only accelerated since: active ETF assets in Europe reached €108.3 billion by mid-2026 – almost triple their level at the end of 2023 – with active strategies accounting for 8.8% of all European ETF inflows, up from 7.3% in 2024.
Even so, active ETFs still represent only around 3–3.4% of total European ETF assets, against roughly 12.5% in the US, according to Morningstar and State Street estimates. That gap – driven partly by the tax disadvantages active ETFs face in several European jurisdictions relative to mutual funds — is precisely what most providers point to as the market's remaining headroom.
Why institutional flows are moving in
For fund selectors and private banks, the appeal is structural rather than tactical: an active mandate delivered inside a listed, intraday-liquid, typically lower-cost wrapper, with the transparency of daily holdings disclosure. Bond ETFs illustrate the shift well – active fixed income strategies gathered around €5 billion in the first half of 2026, or 27% of active ETF inflows, up from just 10% in 2024, as providers increasingly treat fixed income as a natural fit for active management rather than passive replication.
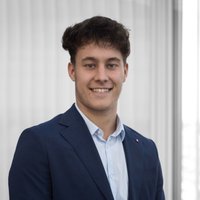
Florian Roemers, CAIA, Fund Analyst at Belfius AM, frames the appeal in similar terms: The growth of active ETFs is one of the more interesting developments in fund distribution, particularly as investors increasingly expect transparency, liquidity and cost efficiency alongside active management.
More choice does not mean better choice
The provider landscape is also concentrating even as it expands. J.P. Morgan remains the largest active ETF provider in Europe with a 42.1% market share, and the top five providers together account for 71% of all active ETF assets – a reminder that rapid product growth has not translated into a proportionally wider opportunity set for selectors.
That tension is exactly where Roemers sees the due diligence challenge sitting: From a third-party fund-selection perspective, the rise of active ETFs also creates a challenge: more choice does not necessarily mean better choice. A rigorous due diligence process is needed as the primary objective remains the consistency of the manager to generate alpha across different market regimes.
AI as an augmentation tool, not a replacement
As the active ETF universe expands, selectors are also absorbing a growing volume of manager, portfolio and risk data – precisely the workload artificial intelligence tools are increasingly being deployed against, from screening to portfolio analytics.
Roemers is clear about where he draws the line: I see AI as a powerful augmentation tool rather than a replacement for the fund selector. AI will increasingly help us deal with the growing amount of information, from screening and portfolio analytics to identifying changes in a manager's positioning or risk profile. But I don't see it replacing qualitative due diligence where the human element remains essential. Understanding how a manager thinks, how a team behaves under pressure and whether the stated process is actually reflected in the portfolio cannot be reduced to a dataset.
Evolution, not revolution
Taken together, the two trends reinforce rather than compete with each other, in Roemers' view: I see the combination of AI and active ETFs as an evolution rather than a revolution. The technology can make fund selection more scalable, while the ETF structure can make active strategies more accessible. But ultimately, the quality of the underlying investment process remains what determines whether a fund deserves a place in a portfolio.
That framing matters for how selectors should read the headline growth figures. Faster launches and rising inflows do not, on their own, validate a strategy's ability to generate alpha across different market regimes – the condition Roemers identifies as the one that would make the current wave of enthusiasm premature if managers cannot sustain it through a full cycle.
The bottom line
The rise of active ETFs is real, structural and still under-penetrated in Europe relative to the US. But for selectors, bankers and asset managers, the distribution story and the due diligence story are separate questions. AI can compress the screening and monitoring workload; it cannot substitute for the qualitative judgment that determines whether a manager's process, team and positioning justify a place in an institutional portfolio.
This article is for informational purposes only and does not constitute investment advice.
Sources: EFAMA, Morningstar, State Street, LSEG Lipper Alpha, Florian Roemers (Belfius AM)