Emerging market fixed income: resilience amid the global bond sell-off

28 SEPT, 2026
By Guillaume Tresca from Generali Investments


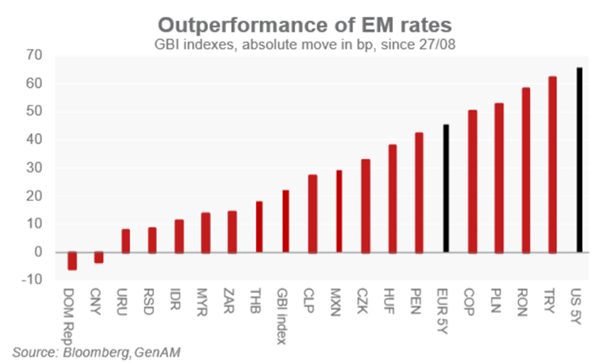
Emerging market fixed income has not been spared from the global bond sell-off, but it has clearly outperformed developed market rates since the end of August. Likewise, emerging market sovereign spreads have remained broadly stable. This outperformance confirms our long-held view on the resilience of emerging markets, underpinned by structural macroeconomic improvements. In addition, central banks in these markets are ahead in the hiking cycle, which provides a degree of stabilisation at the long end of the curve. Positive technicals are also playing a role, with strong inflows into the asset class and emerging market funds maintaining acceptable liquidity levels. This resilience can persist as long as the US dollar does not appreciate significantly.
We continue to prefer local currency debt over hard currency debt. It offers more attractive valuations, and the recent repricing of local rates provides better entry points. We favour high-yielders. In hard currency debt, returns should be positive but will be driven mainly by carry. Duration risk persists and spreads are close to multi-year lows, leaving limited room for further tightening. We see most of the value in the BB segment.