VanEck: The New Arms Race is a Metals Race

24 SEPT, 2026
By VanEck


Marketing communication
Global rearmament is a metals race in disguise. Defense budgets are surging, hardware drives the spend, and China controls the supply.
After the Cold War, Western nations scaled back defense investment and industrial capacity.i Today the US builds just 0.1% of the world's ships and barely a third of its target submarines.ii The strain became clear in the 2026 Iran campaign, when the US fired over 2,100 cruise missiles that it cannot replace for years.iii China absorbed much of that capacity, increasing Western reliance on a strategic rival.
The Rearmament Surge
Global defense spending jumped 9.7% in real terms in 2024 and reached $2.9 trillion in 2025, with Europe leading the surge.iv At NATO's 2025 Summit, 31 of 32 members pledged 5% of GDP by 2035 — more than double today's guideline.v The US alone is requesting $1.5 trillion for 2027, the largest military buildup since WWII and a 44% increase over 2026.vi
Hardware Means Metals
NATO members now direct 32% of budgets to procurement; if the 5% pledge is met, spending over the next decade could approach $30 trillion, with nearly $10 trillion on hardware alone.vii Please note that such projections may not materialise, and there is a risk of losing all or part of the investment.
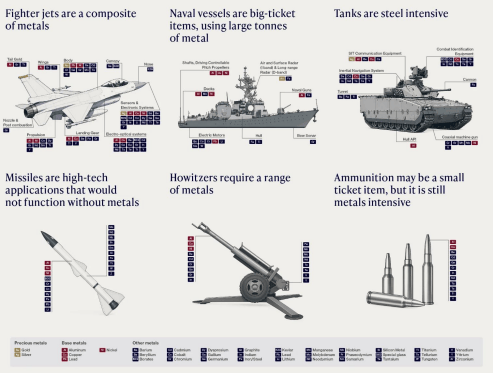
Behind this hardware buildout lies another strategic requirement: metals. Fighter jets, destroyers and missiles rely on the same critical metals. The article examines four key ones:
• Steel — the backbone of naval vessels, with specialty grades controlled by just a handful of mills.
• Copper — military production consumed over 10% of the world's refined copper output in 2021, compounding roughly 14% a year since.viii Drone- and missile-heavy warfare further increases the demand.
• Aluminum — a key input for drones, cruise missiles, and lightweight munitions, with rising demand and constrained Western production capacity drawing strategic attention.
• Rare Earths & Minor Metals — China produces 97% of the world's samarium, 98% of gallium, and 83% of tungsten, and has restricted exports of gallium, germanium, and antimony, with the block on military buyers remaining even after a 2025 trade truce.ix US law banning Chinese-sourced defense magnets takes effect in 2027, accelerating the need for domestic alternatives.x
Key Metals and Minerals Inside Major Defense Systems
Source: The Hague Centre for Strategic Studies (2020). “Strategic Raw Materials for Defence: Mapping European Industry Needs”.
Three VanEck Funds to Access the Theme
1. VanEck Defense UCITS ETF — tracks the MarketVector™ Global Defense Industry Index, offering exposure to defense contractors and platform manufacturers. Yet, the fund is subject to risks associated with investing in the defense sector, including sector concentration, geopolitical and regulatory risks.
2. VanEck Rare Earth and Strategic Metals UCITS ETF — tracks the MVIS® Global Rare Earth/Strategic Metals Index, covering miners, refiners, and processors of rare earths and minor metals — a critical part of the value chain facing significant supply constraints. Investing in natural resources companies involves risks including commodity price volatility, geopolitical developments and exposure to emerging markets.
3. VanEck S&P Global Mining UCITS ETF — tracks the S&P Global Mining Reduced Coal Index, offering exposure across diversified producers of iron ore, copper, and aluminum — a more diversified but also more cyclical route into the rearmament demand story. Risks associated with the Fund include commodity price volatility, cyclical market conditions and exposure to emerging markets.
Rearmament is not only a defense story — it is also a materials story. As governments rebuild military capacity, strategic metals are becoming increasingly important inputs, creating potential opportunities across defense, mining and critical materials. The pace and scale of this trend may vary over time, while geopolitical, commodity and broader market developments will continue to shape the investment landscape.
IMPORTANT INFORMATION
This is a marketing communication.
For investors in Switzerland: VanEck Switzerland AG, with registered office in Genferstrasse 21, 8002 Zurich, Switzerland, has been appointed as distributor of VanEck´s products in Switzerland by the Management Company VanEck Asset Management B.V. (“ManCo”). The representative in Switzerland is Zeidler Regulatory Services (Switzerland) AG, Stadthausstrasse 14, CH-8400 Winterthur, Switzerland. Swiss paying agent: Helvetische Bank AG, Seefeldstrasse 215, CH-8008 Zürich.
For investors in the UK: This is a marketing communication targeted at Professional Clients and Eligible Counterparties - wealth managers, FCA regulated financial intermediaries. This is not for distribution or reliance by Retail Clients. VanEck Securities UK Limited (FRN: 1002854) is an Appointed Representative of Strata Global Limited (FRN: 563834), which is authorised and regulated by the Financial Conduct Authority (FCA) in the UK, to distribute VanEck´s products to FCA regulated firms. The Funds are recognised in the UK under the Overseas Funds Regime but are not UK-authorised Fund. UK investors should note that complaints in relation to the Funds cannot be referred to the Financial Ombudsman Service, and any related claims for losses will not be covered by the Financial Services Compensation Scheme. The information contained in this communication is not a personal recommendation and does not take account of the investment objectives, financial situation or needs of any specific recipient. This information originates from VanEck (Europe) GmbH, which is authorized as an EEA investment firm under the Markets in Financial Instruments Directive (“MiFiD”). VanEck (Europe) GmbH has its registered address at Kreuznacher Str. 30, 60486 Frankfurt, Germany, and has been appointed as distributor of VanEck products in Europe by the ManCo, which is incorporated under Dutch law and registered with the Dutch Authority for the Financial Markets (AFM). This material is only intended for general and preliminary information and does not constitute an investment, legal or tax advice. VanEck (Europe) GmbH and its associated and affiliated companies (together “VanEck”) assume no liability with regards to any investment, divestment or retention decision on the basis of this information. All relevant documentation must be first consulted. The views and opinions expressed are those of the author(s) but not necessarily those of VanEck. Opinions are current as of the publication date and are subject to change with market conditions. Information provided by third party sources is believed to be reliable and has not been independently verified for accuracy or completeness and cannot be guaranteed.
VanEck Defense UCITS ETF ("ETF") is a sub-fund of VanEck UCITS ETFs plc, a UCITS umbrella investment company with limited liability between sub-funds. The ETF is registered with the Central Bank of Ireland, passively managed and tracking an equity index. VanEck S&P Global Mining UCITS ETF ("ETF") is a sub-fund of VanEck UCITS ETFs plc, a UCITS umbrella investment company, registered with the Central Bank of Ireland, passively managed and tracking an equity index. VanEck Rare Earth and Strategic Metals UCITS ETF ("ETF") is a sub-fund of VanEck UCITS ETFs plc, a UCITS umbrella investment company, registered with the Central Bank of Ireland and tracking an equity index.
The value of the ETF may fluctuate significantly as a result of the investment strategy. The ETF´s holdings are disclosed on each dealing day on www.vaneck.com under the ETF´s Holdings section and as per PCF under the Documents section and published via one or more market data suppliers. The indicative net asset value (iNAV) of the ETF is available on Bloomberg. For details on the regulated markets where the ETF is listed, please refer to the Trading Information section on the ETF page at
www.vaneck.com. Investors must buy and sell units of the UCITS on the secondary market via an intermediary (e.g. a broker) and cannot usually be sold directly back to the UCITS. Brokerage fees may incur. The buying price may exceed, or the selling price may be lower than the current net asset value. Investing in the ETF should be interpreted as acquiring shares of the ETF and not the underlying assets. Tax treatment depends on the personal circumstances of each investor and may vary over time. The ManCo may terminate the marketing of the ETF in one or more jurisdictions. The summary of the investor rights is available in English at: summary-of-investor-rights.pdf.
Please refer to the Prospectus – in English language - and the KID/KIID - in local language - before making any final investment decisions and for full information on risks. These documents can be obtained free of charge at www.vaneck.com, from the ManCo or from the appointed facility agent.
The MarketVector™ Global Defense Industry Index is the exclusive property of MarketVector Indexes GmbH (a wholly owned subsidiary of Van Eck Associates Corporation), which has contracted with Solactive AG to maintain and calculate the Index. Solactive AG uses its best efforts to ensure that the Index is calculated correctly. Irrespective of its obligations towards MarketVector Indexes GmbH (“MarketVector”), Solactive AG has no obligation to point out errors in the Index to third parties. VanEck’s ETF is not sponsored, endorsed, sold or promoted by MarketVector and MarketVector makes no representation regarding the advisability of investing in the ETF. It is not possible to invest directly in an index.
The S&P Global Mining Reduced Coal Index is a product of S&P Dow Jones Indices LLC and its affiliates (“SPDJI”). S&P®, is a trademark of S&P Global, Inc. or its affiliates (S&P) and has been licensed for use by VanEck. Dow Jones® is a registered trademark of Dow Jones Trademark Holdings LLC (“Dow Jones”). VanEck’s ETF is not sponsored or sold by SPDJI, Dow Jones, S&P, or their respective affiliates and none of such parties make any representation regarding the advisability of investing in such product(s) nor do they have any liability for any errors, omissions, or interruptions of the S&P Global Mining Reduced Coal Index. It is not possible to invest directly in an index.
MVIS® Global Rare Earth/Strategic Metals Index is the exclusive property of MarketVector Indexes GmbH (a wholly owned subsidiary of Van Eck Associates Corporation), which has contracted with Solactive AG to maintain and calculate the Index. Solactive AG uses its best efforts to ensure that the Index is calculated correctly. Irrespective of its obligations towards MarketVector Indexes GmbH (“MarketVector”), Solactive AG has no obligation to point out errors in the Index to third parties. VanEck’s ETF is not sponsored, endorsed, sold or promoted by MarketVector and MarketVector makes no representation regarding the advisability of investing in the ETF. It is not possible to invest directly in an index.
Investing is subject to risk, including the possible loss of principal. For any unfamiliar technical terms, please refer to ETF Glossary | VanEck. No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission of VanEck.
© VanEck (Europe) GmbH ©VanEck Switzerland AG © VanEck Securities UK Limited
i U.S. Department of Defense, “Strategic and Critical Materials in the Defense National Stockpile,” Report to Congress, December 1998
ii J.P. Morgan, “U.S. Defense Industrial Base,” Revised Edition, 2026; Congressional Budget Office, Challenges Facing the Navy’s and Coast Guard’s Shipbuilding Programs, April 2026. iii CBS News, “Rapid pace of interceptor and precision-guided weapons use worries Trump administration,” July 23, 2026.
ivStockholm International Peace Research Institute (SIPRI), Trends in World Military Expenditure, 2025, April 2026.
v NATO Hague Summit Declaration, June 2025.
vi U.S. Department of Defense, FY2027 Budget Request Overview Book, April 2026; White House, “Rebuilding Our Military: FY2027 Budget Fact Sheet,” April 2026.
vii NATO, Defence Expenditure of NATO Countries (2014–2025), Table 8a, August 2025.
viiiGregory Wischer, Morgan Bazilian and Macdonald Amoah, “As America’s Military Rearms, It Needs Minerals—and Lots of Them,” Modern War Institute at West Point, 29 November 2023. https://mwi.westpoint.edu/as-americas-military-rearms-it-needs-minerals-and-lots-of-them/
ix Christopher Hernandez-Roy, Henry Ziemer and Alejandra Toro, “Mining for Defense: Unlocking the Potential for U.S.-Canada Collaboration on Critical Minerals,” Center for Strategic and International Studies (CSIS), 18 February 2025.
x Financial Times, “Defence groups clamour to delay US ban on Chinese rare earth magnets,” May 2026.