Sébastien Gandon (BLI): ‘The true risk is no longer volatility, but the erosion of purchasing power’

29 OCT, 2026
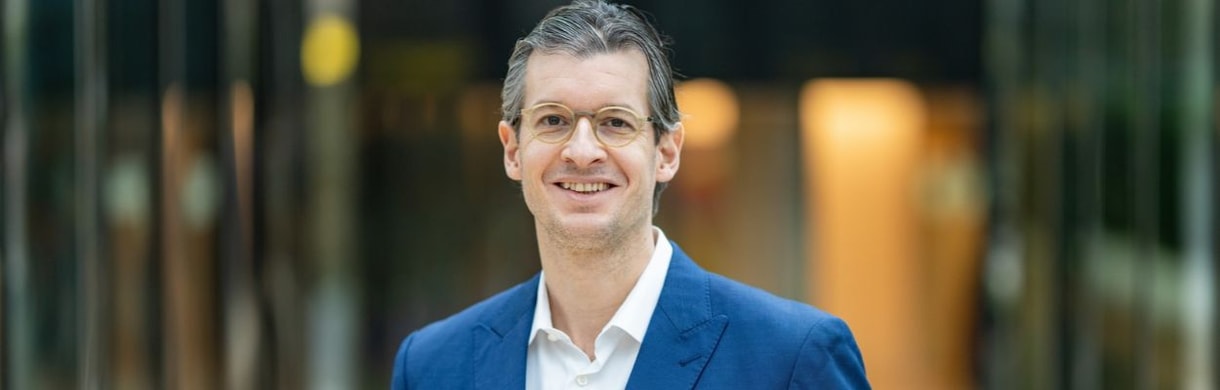


With oil rising, bond yields climbing and the AI trade drawing closer scrutiny, investors face an environment where protecting capital matters as much as growing it. In this interview, Sébastien Gandon, Senior Client Portfolio Manager at BLI – Banque de Luxembourg Investments, explains why the firm favours real assets, quality stocks and gold in an era of structurally higher inflation. He also points to opportunities in cyclicals, Latin American assets and the yen, sets out a cautious, tactical approach to AI, and describes how BLI is rethinking risk in multi-asset portfolios such as BL-Global 30.
Where do you see the most attractive investment opportunities in the current volatile macroeconomic and geopolitical environment?
Over the long run, avoiding losses is the essential precondition for sustainable value creation. In a more uncertain environment where the primary risk is monetary depreciation, this conviction translates into a preference for real assets, quality stocks and gold. In the near term, oil prices have certainly been rising, but so far at a pace that we believe the economy can absorb: the speed of the move matters as much as its direction. Earnings remain solid, so the real question for equities is multiples, and therefore rates, given the strong correlation between the two over the past five years.
We currently see opportunities in the following segments: cyclicals and capex-related stocks – in a context of accelerating economy but higher interest rates that weigh on consumption–, Latin American assets (supported by a combination of positive factors such as rising commodities prices, a weakening dollar, potential for monetary easing, more business-friendly policies, attractive valuations…) and the yen. Notably, joint currency interventions between the United States and Japan have historically marked a change of paradigm and a reversal in the yen.
Following this year’s sharp rally, does gold still play a role as a portfolio hedge?
Gold has become a core component of our portfolios, as a hedge against inflation and the erosion of confidence in fiat currencies. We initiated our first positions in 2012 in our balanced funds, following the former ECB's President Mario Draghi 'whatever it takes' statement.
We now find ourselves in an era of structurally higher inflation, compounded by heavy sovereign indebtedness that prevents governments from sustaining restrictive monetary policy for long. Gold offers direct protection against this scenario. Despite the recent price rally and heightened volatility in gold since the start of the year, several structural factors continue to justify this exposure: excessive levels of public debt, growing distrust towards the dollar, and the risk of debt monetization.
How should investors approach growth driven by artificial intelligence without paying an excessive price for it?
The AI-driven investment cycle is real and is still supporting growth: capital expenditure continues to rise, memory prices are fuelling a semiconductor super-cycle and capital markets remain open to the sector. But the theme is approaching a crossroads. Hyperscalers' spending is increasingly financed by debt, and credit spreads are widening, not only for the most fragile players but also for the leaders. History shows that those who finance a transformation at its peak rarely reap the rewards. Moreover, the market is no longer treating AI as a homogeneous bloc: the cash flows of hyperscalers and chipmakers, for instance, have followed very different trajectories recently. It is therefore critical to be discerning. For now, we exercise caution: we recommend no longer overweighting the theme and approaching it tactically.
Given the rise in bond yields in Europe and the US, how are you positioning yourself in fixed income?
Over the long term, we favour real assets. With public debt this high, G7 government bonds are likely to deliver negative real returns, so we no longer see them as a core source of return. In our balanced funds they keep a structural role as protection against deflation; elsewhere, we use them tactically. That said, after the recent sell-off, several factors suggest yields have found a ceiling, at least cyclically, so it may make sense to gradually rebuild sovereign bond exposure and lengthen duration. How far we go depends mainly on the correlation between equities and rates: when both fall together, bonds offer only false diversification. When we add duration, we prefer very long maturities, which avoid tying up too much capital. We also seek yield selectively when conditions align, for example in Latin American local-currency debt.
What are the most resilient sources of long-term returns for defensive and multi-asset portfolios such as BL-Global 30?
The structural shifts in the economic and financial environment require a fundamental rethinking of risk. The past four decades were shaped by strong growth, contained inflation, and rising globalization, driving interest rates lower and generating strong returns across both equities and bonds. That golden age, where any combination of stocks and bonds delivered regardless of valuation, is behind us. In an environment of structural currency debasement, the true risk is no longer short-term price fluctuation but the long-term erosion of purchasing power. Volatility remains a source of discomfort, but it is the price to pay for protecting purchasing power. Spanish savers know this well: in the late 1970s, inflation above 20% eroded the savings of an entire generation, and the peseta was devalued three times in less than a year during the 1992-93 ERM crisis.
Disclaimer
This document is issued by BLI - Banque de Luxembourg Investments (“BLI”), with the greatest of care and to the best of its knowledge and belief. The views and opinions published in this publication are those of the authors and shall not be binding on BLI. Financial and economic information published in this publication are communicated for information purposes only based on information known on the date of publication. Such information does not constitute investment advice, recommendation or encouragement to invest, nor shall it be interpreted as legal or tax advice. Any information should be used with the greatest caution. BLI does not give any guarantee as to the accuracy, reliability, recency or completeness of this information. BLI’s liability cannot be invoked as a result of this information or as a result of decisions that a person, whether or not a client of BLI, may take based thereon; such persons retain control over their own decisions. Interested persons must ensure that they understand the risks involved in their investment decisions and should refrain from investing until they have carefully considered, in conjunction with their own professional advisors, the appropriateness of their investments to their specific financial situation, in particular with regard to legal, tax and accounting aspects. It is reiterated that the past performance of a financial instrument is no guarantee of future returns. BLI - Banque de Luxembourg Investments investment solutions are distributed by La Française Finance Services, with registered office at 128 boulevard Raspail, 75006 Paris, France. La Française Finance Services is regulated by the Autorité de Contrôle Prudentiel et de Résolution (ACPR) as an investment services provider under number 18673 and is a subsidiary of La Française.