Carmignac Investissement: a well-differentiated global equity strategy

15 SEPT, 2026
By Joanna Piwko from RankiaPro Europe
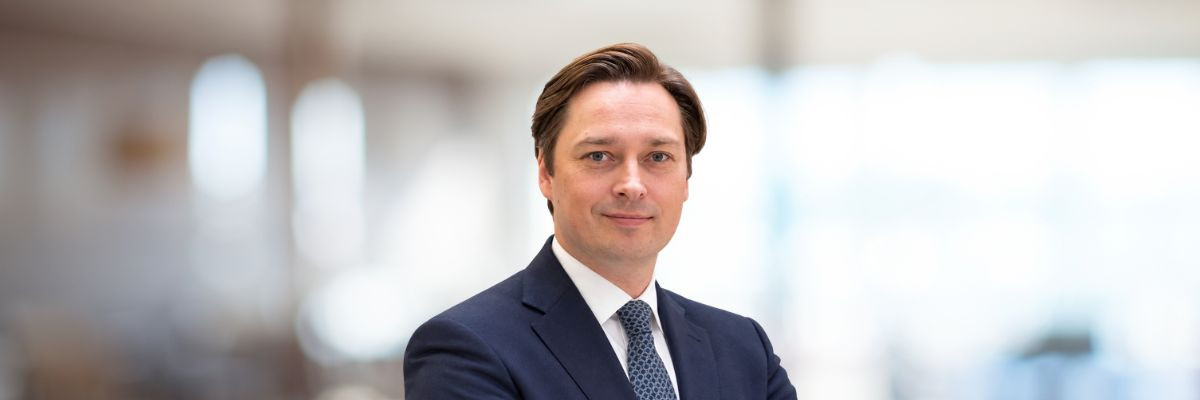


The major structural trends of global equity markets, from artificial intelligence to emerging markets, do not automatically translate into simple portfolio choices: they require a method capable of distinguishing the companies that will truly benefit from those only apparently exposed. We discuss this with Kristofer Barrett, manager of the Carmignac Investissement fund.
During the interview, Barrett outlines the fund's strongest convictions, from the AI cycle to the structural weight of emerging markets, explains the role of EV/FCF in stock selection compared to traditional multiples, describes the balance between concentration and diversification on about 80 positions, and addresses the issue of SMID cap and the challenges that agentive AI poses to the software sector.
Considering the global equity universe as a whole, what are your strongest convictions today in defining the portfolio positioning?
Our strongest conviction remains the investment cycle in artificial intelligence. The demand for computing power continues to grow rapidly, with strong earnings growth across the semiconductor ecosystem. However, we are increasingly focusing on where the economic value generated by these investments will end up concentrating. Hyperscalers are allocating unprecedented amounts of capital to AI infrastructure, putting pressure on free cash flow. The key question is whether they are investing because they want to or because competitive pressure forces them to do so. What is clearer is where this capital is converging: in hardware, semiconductors and the broader value chain of AI infrastructure. Beyond AI, we also maintain exposure to more defensive sectors, such as healthcare distribution. These assets have generally performed well in periods when AI-related stocks are under pressure.
Emerging markets remain a structural component of the portfolio. What is the logic behind this exposure today and where, within emerging markets, are your strongest convictions concentrated?
At the end of August, emerging markets represented about 26% of the portfolio, roughly double their weighting in the MSCI ACWI1 index. This reflects a selection of bottom-up stocks rather than a top-down allocation. We invest in the region because we believe it offers a wide range of high-quality companies with interesting long-term growth prospects, despite often being overlooked by some investors due to perceived volatility. Emerging markets are also fundamental to the value chain of artificial intelligence. Taiwan, which represents about 15% of the portfolio, is crucial for advanced semiconductor production, while South Korea, with about 6%, is a leader in the high-bandwidth memory sector. Beyond AI, we identify interesting opportunities in the consumer goods and financial services sectors, including MercadoLibre, Sea, Allegro and Itaú2. These companies benefit from structural trends such as digital adoption, the progressive formalization of financial services, favorable demographics, and the ongoing development of still underpenetrated domestic markets in Latin America, Asia and Central Europe.
The fund uses EV/FCF (Enterprise Value/Free Cash Flow) as a central parameter instead of traditional earnings multiples. How does this approach translate into balancing between higher growth stocks and stocks characterized by more moderate growth but interesting valuations?
The use of EV/FCF allows us to compare companies with very different growth profiles on a common basis: the cash flow they can ultimately generate relative to their enterprise value. Unlike traditional earnings multiples, this indicator also takes into account the balance sheet structure and capital intensity, making it particularly useful for different business models. In practice, this favors a balanced approach. On the one hand, we invest in companies like McKesson and Cencora2, which offer moderate but highly visible growth, solid free cash flow generation and interesting valuations. Their defensive activities in the healthcare sector benefit from recurring demand and generate resilient cash flows. On the other hand, we are willing to accept higher valuations where we believe that structural growth can lead to much stronger expansion of future free cash flow. Nvidia and Broadcom2 are excellent examples, thanks to their ongoing investments in AI infrastructure.
The fund holds about 80 stocks, a number designed to balance conviction and diversification. How do you decide how much risk to concentrate on the highest conviction ideas versus maintaining a more diversified portfolio?
The size of the positions does not simply depend on conviction. It also reflects the valuation, the downside risk, the liquidity and the contribution of each title to the overall portfolio risk. We want our highest conviction ideas to have a significant impact on performance, while avoiding excessive dependence on a single company, a theme or a market factor. Diversification therefore comes from the combination of companies characterized by different earnings drivers and risk profiles, rather than simply owning a large number of stocks. This is particularly important when market leadership can change quickly, even within strong structural themes such as artificial intelligence. We also maintain the flexibility to invest outside of our main convictions when valuations become interesting. After a sharp price drop, we might open a small position when we believe the market is excessively penalizing a company's fundamentals, and then strengthen it progressively as our conviction increases. Zoetis and Uber are two good examples2. On the contrary, when a stock reaches what we consider fair value, we are willing to realize gains and reduce or close the position.
About a quarter of the stocks in the portfolio are not included in the MSCI AC World index. What kind of research process do you use to identify these less followed opportunities?
The fact that about a quarter of the portfolio is outside the MSCI AC World index is not a goal in itself, but the result of our bottom-up research process. When we identify a structural trend, we analyze the entire value chain rather than focusing exclusively on the largest and most obvious beneficiaries. For each theme, we look for bottlenecks, the power to determine prices, barriers to entry, and products difficult to replace for customers. This often leads us towards smaller or less followed companies that play a fundamental role in an ecosystem but receive limited coverage from analysts. Our research is strongly focused on fundamentals and is collaborative. Together with the broader Carmignac investment team, assumptions are verified through discussions with the company's management teams, suppliers, customers, competitors, and local industry specialists. The goal is to understand not only a company's fundamentals, but also how its position within the value chain is evolving and whether its competitive advantage is sustainable.
What do you look for in a SMID cap that, in your opinion, is not yet correctly valued by the market due to limited analyst coverage? Within the semiconductor ecosystem, the fund has identified interesting opportunities among suppliers of critical materials along the supply chain.
A distinctive feature of the portfolio is its exposure to SMID cap companies. Like emerging market companies, these firms can be overlooked by the market because they receive less analyst coverage and have lower visibility compared to large-cap companies in developed markets. We seek niche leaders with a lasting competitive advantage, solid balance sheets, a strong ability to generate cash, and products or services that are difficult to replace. At the end of August, the portfolio held over 20 SMID cap companies, accounting for about 10% of the portfolio. The Japanese company Nitto Boseki produces specialized fiberglass and electronic materials, including T-glass used in advanced semiconductor packaging, and is a great example of a SMID company. As processors and high-bandwidth memories are arranged in ever smaller spaces, these materials help improve reliability and control thermal expansion. Its manufacturing expertise is difficult to replicate, making it an under-recognized beneficiary of investments in AI infrastructure. This exposure to SMIDs also helps us build a more agile and diversified portfolio, particularly in a context where global equity indices remain highly concentrated.
Where do you see the greatest "off the beaten path" opportunities in the AI value chain today, beyond chip manufacturers and hyperscalers?
Beyond chip manufacturers and hyperscalers, we see interesting opportunities among the less visible companies that provide the tools, materials, and infrastructure necessary to translate AI-related demand into actual computing capacity. As computing systems become more powerful and complex, bottlenecks emerge in semiconductor production, advanced packaging, connectivity, and cooling. The scope of investments is significant. TSMC spent $15.7 billion in capital expenditures in the second quarter of 20263, while Intel continues to invest heavily in production capacity. This supports demand along the broader semiconductor supply chain. In the equipment segment, DISCO provides precision tools used for cutting, grinding, and thinning wafers, while Grand Process Technology provides equipment for cleaning, etching, and plating for advanced packaging. We also see opportunities in enabling materials and connectivity: JX Advanced Metals produces high-purity semiconductor materials, Sumitomo Electric develops optical components for faster data transmission, and LOTES provides high-speed connectors and components for liquid cooling intended for artificial intelligence servers2.
Software sector stocks have undergone a broad contraction of valuation multiples, despite solid competitive positions. As agent-based AI advances, what characteristics distinguish software companies that will be able to preserve their value from those exposed to the risk of disintermediation?
Agentive AI will create clear winners and losers in the software sector. We favor companies integrated into mission-critical workflows, with proprietary data, high supplier replacement costs, and direct access to a broad consolidated customer base. These advantages should help them integrate AI into existing products and generate measurable productivity increases. Conversely, generic solutions dedicated to single functions and solutions that merely add a simple layer to third-party models appear more exposed to the risk of losing differentiation and becoming easily replaceable. Atlassian embodies the characteristics we are looking for. Jira, Confluence and Jira Service Management2 are at the center of critical workflows, allowing the company to access the organizational context that AI agents need to automate processes, while its installed base provides a natural distribution channel for new AI features. However, competition from operators specifically born in the AI ecosystem remains intense and monetization is still uncertain. Valuations are also not particularly convenient: the S&P 500 Software index is traded at about 25 times expected earnings in a year, compared to about 19.5 times for the S&P 5004. We therefore maintain limited exposure to software sector securities.
1. Source: Carmignac, 31/08/2026. Benchmark index: MSCI AC World NR index. The portfolios of Carmignac funds can be changed without any notice.
2. The reference to certain securities and financial instruments is illustrative, in order to highlight the securities that are or have been included in the portfolios of the Carmignac range funds. This reference is therefore not intended to promote direct investment in these instruments nor does it constitute investment advice. The Management Company is not subject to the prohibition of trading these instruments before the publication of the communication. The portfolios of Carmignac funds can be changed without any notice.
3. Source: Yahoo Finance, 31/08/2026. This reference is therefore not intended to promote direct investment in these instruments nor does it constitute investment advice.
4. Source: Bloomberg, 31/08/2026. The portfolio is subject to changes without notice.
Marketing communication. Please consult the KID/prospectus before making a final investment decision. This document is intended for professional clients.
1.Carmignac Investissement A EUR Acc: Minimum recommended investment period 5 years; Risk level 4/7. KID Risk Scale (document containing key information). Risk 1 does not mean that the investment is risk-free. This indicator can evolve over time. Main risks of the Fund: Equity: The variations in the price of shares, which depend on external economic factors, the volume of securities traded and the level of capitalization of companies, can affect the performance of the Fund. Exchange: The exchange risk is connected to the exposure, through direct investments or using derivative financial instruments, to a currency different from that of the Fund's valuation. Discretionary Management: The forecasts on the trend of financial markets made by the management company have a direct impact on the performance of the Fund, which depends on the selected securities. Investing in the Fund could involve a risk of capital loss. To consult the complete list of risks, refer to the Fund Prospectus. This document cannot be reproduced, in whole or in part, without the prior authorization of the Management Company. This document does not constitute either a subscription offer or investment advice. It does not intend to provide tax, legal or accounting advice and should not be used in this sense. This document is provided for informational purposes only and should not be used to assess the suitability of an investment in securities or shares illustrated therein or for any other purpose. The information contained in this document may be partial and may be changed without notice. They are updated to the date of drafting of this document and are taken from proprietary and non-proprietary sources considered reliable by Carmignac. They are not necessarily exhaustive or accurate. Consequently, Carmignac, its officers, employees or agents do not guarantee their accuracy or reliability and decline all responsibility in case of errors and omissions (including liability to third parties in case of negligence). The decision to invest in said fund should take into account all its objectives and its characteristics described in the related prospectus. The reference to specific securities or financial instruments is given merely as an example to illustrate securities currently or previously present in the portfolios of the Carmignac range Funds. This reference is therefore not intended to promote direct investment in these instruments nor does it constitute investment advice. The Management Company has the power to carry out transactions with these instruments before the publication of the communication. The portfolios of the Carmignac Funds can be modified at any time. The reference to specific securities or financial instruments is given merely as an example to illustrate securities currently or previously present in the portfolios of the Carmignac range Funds. This reference is therefore not intended to promote direct investment in these instruments nor does it constitute investment advice. The Management Company has the power to carry out transactions with these instruments before the publication of the communication. The portfolios of the Carmignac Funds can be modified at any time.
This document is not intended for individuals in jurisdictions where (due to the nationality, residence or otherwise of such individual) the document or the availability of such document are prohibited. Individuals to whom such prohibitions apply must not have access to this document. Taxation depends on the individual investor's situation. The Funds are not registered for retail distribution in Asia, Japan, North America and South America. Carmignac Funds are registered in Singapore under the limited foreign scheme (exclusively for professional clients). The Funds are not registered under the U.S. Securities Act of 1933. The Funds may not be offered or sold, directly or indirectly, for the benefit or on behalf of a “U.S. Person” as defined by U.S. Regulation S and FATCA. The risks, fees and expenses applied are described in the KID (Key Information Document). The KID must be delivered to the subscriber before subscription. Read the KID before subscribing. The Funds are not capital guaranteed and investors may lose part or all of their capital. The Funds carry a risk of capital loss. The Funds are French law mutual investment funds (FCP) compliant with the UCITS or AIFM Directive. The Management Company may stop promoting in your country at any time. The Fund's prospectuses, KIDs and annual management reports are available on the website www.carmignac.com/it-it or upon simple request to the Management Company. Investors can access a summary of their rights in Italian at the following link section 5.